
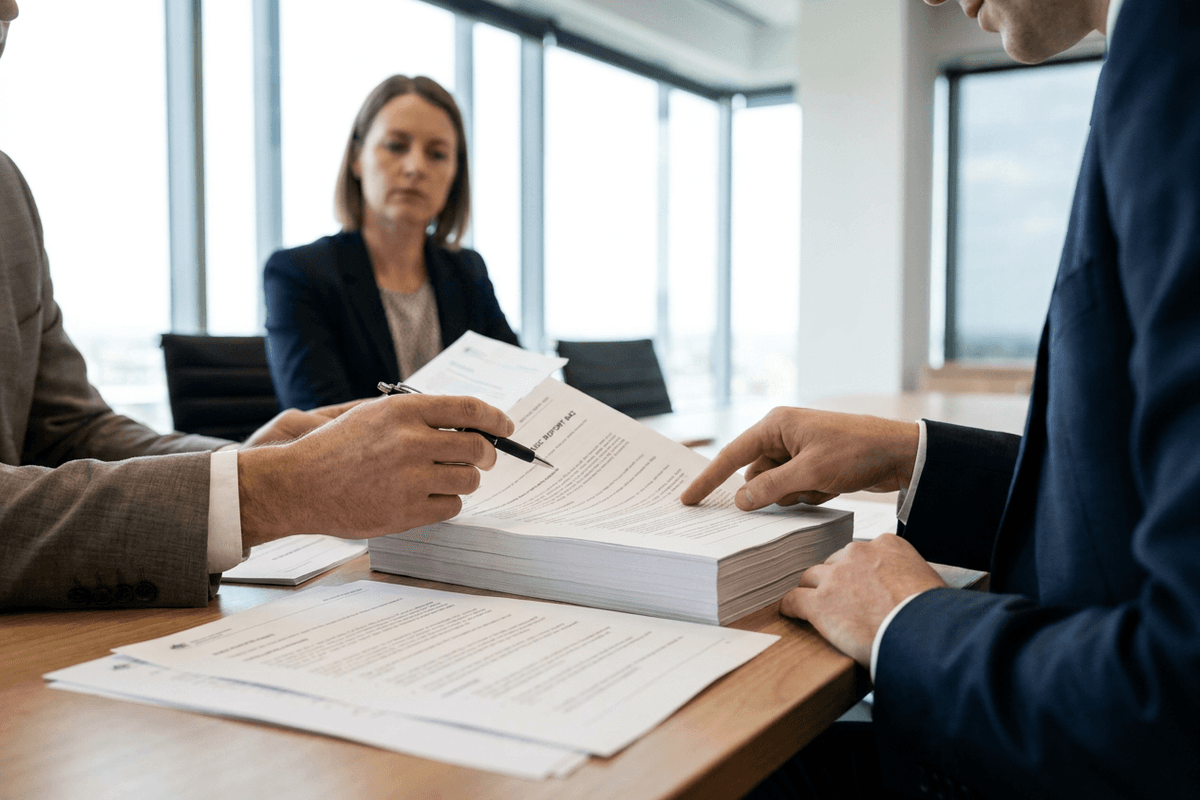
The Australian Securities and Investments Commission (ASIC) has discarded regulatory ambiguity, fundamentally shifting the ground beneath Australia’s audit and financial reporting ecosystem. In its latest surveillance release, ASIC surveillance shows financial reporting and audit quality continues to fall short, accompanying the release of Report 842, the corporate watchdog delivered a direct challenge to the profession. For the first time, ASIC has systematically named major audit firms alongside specific surveillance findings, while calling out entrenched deficiencies in professional judgement, asset valuations, and revenue recognition across both preparers and registered company auditors.
For decades, surveillance findings were masked behind aggregated statistics and de-identified summaries. By attributing audit inspection findings directly to individual firms, the regulator has dramatically elevated the commercial, reputational, and legal stakes of poor file documentation and uncritical acceptance of management forecasts. With corporate boards, audit committees, and practitioners caught in an era of heightened market volatility and shifting discount rates, Report 842 serves as a definitive signal: passive compliance and tick-and-flick assurance will no longer survive regulatory scrutiny.
The Transparency Pivot: From Aggregate Metrics to Direct Attribution
The decision to attribute surveillance findings directly to major firms marks a historic departure in Australian regulatory enforcement. While international counterparts like the UK Financial Reporting Council (FRC) and the US Public Company Accounting Oversight Board (PCAOB) have long published firm-specific inspection reports, Australia’s domestic regime has historically favoured confidential feedback paired with anonymised public syntheses.
That era has officially closed. ASIC’s naming of firms is designed to introduce competitive market tension, empowering audit committees and institutional investors to challenge incumbent auditors on concrete quality indicators rather than polished tender presentations.
"Financial report preparers, directors, and auditors all play vital roles in maintaining the integrity of Australia's financial reporting framework. Transparent market accountability is non-negotiable when professional judgement repeatedly falls short on critical areas like asset carrying values and complex revenue streams."
This public attribution creates immediate governance implications:
- Board Audit Committees (BACs) can no longer rely on standard boilerplate independence and quality declarations during annual tender and reappointment reviews.
- Audit Firm Leadership must re-evaluate internal monitoring under ASQM 1 (Quality Management), shifting from reactive remediation to structural intervention before regulatory inspections uncover systemic partner-level blind spots.
- Preparers and CFOs face a far more inquisitive assurance process, as auditors—wary of public naming—demand deeper empirical substantiation for management's accounting estimates.
The Core Battlegrounds: Asset Valuations and AASB 15
The substantive technical findings within Report 842 home in on two perennial problem areas: asset valuation and impairment testing (AASB 136 / AASB 13), and revenue recognition (AASB 15). While reporting standards have been mature for years, ASIC found that both finance teams and assurance practitioners continue to treat these complex judgements with excessive optimism and inadequate skepticism.
1. The Impairment Crucible (AASB 136)
In a higher-for-longer interest rate environment, terminal growth rates and Weighted Average Cost of Capital (WACC) calculations dictate balance sheet survival. Yet, ASIC’s surveillance revealed widespread instances where management models relied on aggressive cash flow turnaround projections that had no historical precedent or operational grounding.
Auditors were frequently found accepting discounted cash flow (DCF) models without independent challenge of key inputs, such as:
- Discount rates failing to reflect sector-specific risk premiums and debt refinancing costs.
- Terminal growth rates that exceeded the long-term sovereign economic growth forecasts.
- Cash-Generating Unit (CGU) allocations deliberately aggregated to mask underperforming assets behind profitable business units.
2. Revenue Recognition Friction (AASB 15)
Revenue remains the most susceptible line item to premature recognition and manipulation. In Report 842, ASIC singled out ongoing failure to rigorously identify distinct performance obligations in multi-element customer contracts, particularly across technology, construction, and service industries.
Common failures included premature upfront recognition of variable consideration, improper treatment of contract modifications, and an absence of verifiable evidence confirming when control of a good or service transferred to the customer.
Audit Deficiencies vs. Preparer Responsibilities: A Dual Reckoning
A central tenet of ASIC’s communication in Release 26-260MR is that audit quality does not exist in a vacuum. A poor audit often begins with a deficient financial report submitted by management. ASIC reiterated that company directors bear the primary statutory responsibility under the Corporations Act 2001 to deliver financial statements that present a true and fair view.
| Focus Area | Preparer & Management Deficiency | Auditor Assurance Failure | Regulatory Remediation Imperative |
|---|---|---|---|
| Impairment (AASB 136) | Overly optimistic forecast cash flows unsupported by historical execution; stale discount rates. | Failure to independently stress-test WACC; lack of professional skepticism regarding turnaround assumptions. | Engage independent valuation specialists; maintain robust sensitivity matrices covering downside scenarios. |
| Revenue (AASB 15) | Inadequate analysis of contract terms; upfront recognition of unearned or variable consideration. | Over-reliance on management representations; failure to sample underlying customer contracts. | Perform rigorous five-step AASB 15 contract mapping; test controls over contract milestones and billing reconciliations. |
| Subsequent Events (AASB 110) | Failure to update valuations for market deterioration occurring between balance date and signing. | Incomplete review of post-balance sheet management accounts and customer default notifications. | Institutionalise strict dual-signoff procedures up to the exact date of directors' declaration and audit signoff. |
| Disclosures (AASB 101/136) | Omission of key assumptions, discount rates, and sensitivity analysis in the notes to the financial report. | Treating note disclosures as secondary boilerplate rather than primary compliance material. | Audit committees must mandate transparent disclosures showing how changes in assumptions trigger impairments. |
Why Professional Skepticism Is Breaking Down in Practice
Why do these deficiencies persist despite decades of regulatory warnings and extensive continuous professional development? The answers lie at the intersection of resource constraints, firm capacity, and commercial relationship dynamics.
First, Australia’s accounting talent shortage has compressed audit engagement delivery timelines. Senior managers and engagement partners are carrying larger portfolio loads, increasing the temptation to rely on standardized audit workpapers and high-level analytical reviews rather than drilling into complex underlying source data.
Second, there remains a structural hesitancy among engagement teams to challenge longstanding commercial clients on proprietary forecasting models. When a client CFO asserts that next fiscal year’s margin expansion will compensate for current-year headwinds, auditors too often accept the narrative at face value, documenting the assertion as evidence rather than verifying it against external market data.
"Professional skepticism cannot be retrofitted during file closure. It must be demonstrated in the primary audit testing: by asking the difficult questions, verifying management's past forecasting accuracy, and refusing to sign off until assumptions are backed by objective external indicators."
Strategic Action Plan for Australian Practitioners and Finance Leaders
The publication of Report 842 demands immediate, tangible adjustments from corporate finance teams and audit practitioners alike. As ASIC increases the cadence and transparency of its surveillance program, firms must establish operational safeguards to protect their practices and reporting integrity.
For CFOs and Finance Teams
- Formalise Valuations Early: Cease leaving impairment assessments until the year-end crunch. Commission external valuations or complete internal DCF models at the half-year stage, stress-testing them for sustained higher borrowing costs.
- Audit-Proof Your Contracts: For complex, multi-year, or subscription-based revenue agreements, create a standardized AASB 15 assessment memo before billing commences. Document the exact timing of control transfer and clear criteria for variable consideration.
- Re-evaluate Note Disclosures: Treat footnote disclosures as critical protective governance. Ensure sensitivity analyses for impairment clearly explain what percentage change in discount rates or revenue growth would eliminate headroom.
For Assurance Leaders and Audit Partners
- Audit the Track Record: Implement mandatory historical comparison testing. Evaluate management's previous three-year budgets against actual results. If management consistently misses budget targets, their terminal projections cannot be accepted without substantial downward risk weighting.
- Mandate Independent Valuation Reviews: For any engagement where goodwill, unlisted equity, or commercial property forms a material percentage of net assets, mandate the deployment of an independent internal auditor valuation expert to review the discount methodology.
- Enhance ASQM 1 Hot Reviews: Strengthen pre-issuance quality reviews on high-risk files. Engagement Quality Reviews (EQRs) must focus specifically on whether file documentation captures real challenge and pushback against management, rather than passive corroboration.
Looking Ahead: The New Benchmark of Public Accountability
ASIC’s Report 842 has fundamentally altered the compliance landscape. By naming audit firms and highlighting recurrent failures in professional judgement, the regulator has effectively weaponised transparency to drive professional standards upward.
For accounting professionals across Australia, the era of treating surveillance reports as abstract statistical exercises is over. The regulator’s spotlight is now sharply focused on the technical rigour of day-to-day workpapers, the objective defensibility of management forecasts, and the willingness of auditors to stand firm against aggressive accounting treatments. Those who adapt their methodologies and embrace genuine professional skepticism will build resilient, trusted practices; those who treat Report 842 as business as usual do so at immediate peril to their professional reputation and regulatory standing.