


While HM Treasury has moved to dampen speculation regarding a blanket £1.5 million “mansion tax,” the relief across high-net-worth (HNW) advisory corridors has been distinctly measured. As reported by Accountancy Age, ruling out the £1.5 million threshold has not eliminated property tax escalation; rather, it has concentrated fiscal scrutiny squarely onto the £2 million-plus bracket. For UK private client accounting practices, family offices, and tax advisers, the immediate priority is navigating this perilous “grey zone,” where marginal valuation discrepancies can trigger punitive tax surcharges, complex compliance burdens, and aggressive HMRC compliance reviews.
The political decision to steer clear of lower prime bands reflects an acute awareness of London and South East property dynamics, where £1.5 million frequently captures modest family homes. However, properties valued above £2 million remain high-conviction targets for revenue generation. Whether via Stamp Duty Land Tax (SDLT) upper-tier adjustments, Annual Tax on Enveloped Dwellings (ATED) recalibrations, or reformed Council Tax super-bands, private client teams must pivot from speculative concern to concrete wealth protection strategies.
The Fiscal Fault Line: Why the £2m Boundary Endures
The £2 million demarcation is not an arbitrary benchmark in UK tax jurisprudence. It has long functioned as a critical statutory boundary, historically anchoring the introduction of ATED and defining the upper tiers of residential transaction levies. Maintaining focus on the £2 million-plus asset class allows the Chancellor to target liquid and illiquid wealth concentration while minimising broader middle-class voter fallout.
However, the operational problem for practitioners lies in the binary nature of threshold-based taxation. When tax obligations jump sharply upon crossing a specific valuation line, properties appraised between £1.9 million and £2.2 million become acute risk vectors for dispute with HMRC's Valuation Office Agency (VOA).
“Threshold taxation creates artificial cliffs. In prime real estate, a five percent valuation variance determined by HMRC District Valuers can mean the difference between standard compliance and six-figure supplemental liabilities.”
The Quad-Threat Matrix: SDLT, ATED, Council Tax, and CGT
Private client accountants must evaluate four distinct yet interacting property tax mechanisms currently being analysed across the advisory landscape:
| Tax Mechanism | Target Asset Class | Potential Policy Reform | Immediate Practice Impact |
|---|---|---|---|
| SDLT Surcharges | Prime residential transactions (>£2m) | Additional 2–3% marginal top-slice rate or lower cliff thresholds | Slowdown in prime transaction velocity; surge in pre-completion restructuring |
| ATED Scope & Rates | Corporate & enveloped dwellings (>£500k/>£2m) | Annual rate uplifts indexed above CPI; compressed band boundaries | Accelerated de-enveloping reviews and liquidation of non-trading holding companies |
| Council Tax Super-Bands | Properties currently in Band H (>£320k in 1991 values) | Introduction of Bands I & J for modern £2m+ valuations | Increased recurring holding costs; local authority data-sharing with HMRC |
| CGT & PPR Curbs | High-value disposals & large acreage estates | Capping Private Residence Relief (PRR) on gains exceeding £2m | Disruption of primary residence succession planning and estate planning models |
The Valuation Battleground: RICS Standards vs District Valuers
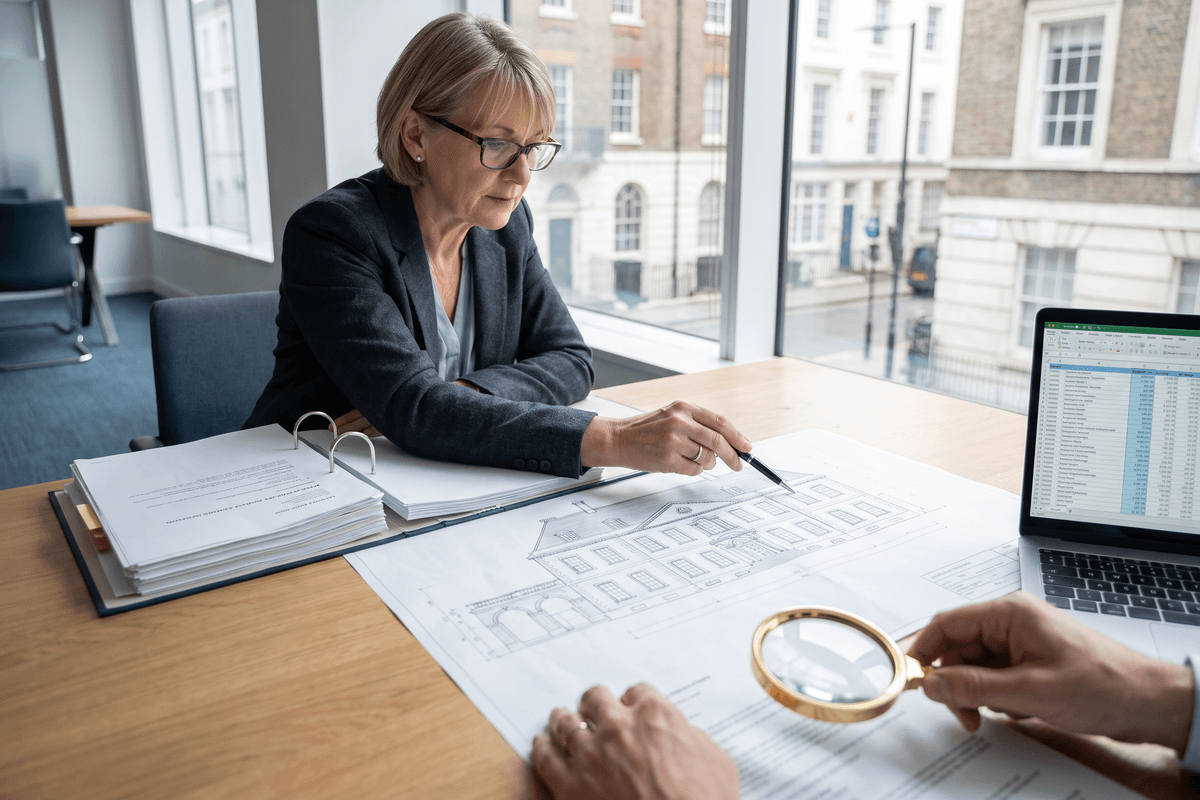
With HMRC intensifying its automated and manual risk profiling, reliance on estate agency estimates is no longer defensible. Borderline properties situated around the £2 million mark require robust, defensible evidence compliant with Royal Institution of Chartered Surveyors (RICS) Red Book standards.
Key Valuation Defence Protocols
- Contemporaneous Red Book Valuations: Commission formal valuations at the precise valuation date rather than relying on retrospective desktop appraisals during an enquiry.
- Separation of Chattels and Fixtures: Accurately document high-value chattels, land apportionments, and commercial or agricultural elements that can legitimately be decoupled from the primary residential dwelling footprint.
- Documenting Latent Defects and Planning Encumbrances: Ensure structural flaws, restrictive covenants, or unviable planning permissions are fully priced into the base valuation to defend against optimistic VOA models.
Advisory Playbook: Structuring, De-Enveloping, and Wealth Architecture
For private client accountants managing substantial portfolios, navigating the £2 million grey zone demands proactive restructuring well ahead of statutory filing deadlines.
1. Strategic De-Enveloping Assessments
Holding residential properties within corporate structures remains punitive under ATED unless covered by genuine commercial letting relief under Section 133 of the Finance Act 2013. For non-let personal residences trapped within corporate shells, firms must model the trade-offs between paying ongoing ATED charges versus incurring upfront Corporation Tax, SDLT, and dividend tax charges upon de-enveloping.
2. Family Investment Companies (FICs) and Mixed-Use Portfolios
While single residential units over £2 million attract maximum scrutiny, incorporating mixed-use assets or diversified commercial holdings within a Family Investment Company structure continues to provide estate planning flexibility. Practitioners should ensure that any residential assets held within corporate or trust vehicles maintain impeccable governance logs proving commercial purpose.
3. Lifetime Gifting and Undivided Share Splitting
Where high-value estates approach the £2 million threshold, gifting undivided fractional shares to adult children or non-spousal family members can fragment single-asset valuations for inheritance tax (IHT) and capital gains purposes. A 10% to 15% discount for co-ownership friction is widely recognised in tax case law, frequently moving individual share valuations beneath critical surcharge triggers.
Actionable Checklist for Practice Leaders
- Audit Prime Residential Client Portfolios: Identify all client properties acquired between £1.75 million and £2.5 million to quantify risk exposure to impending rate changes.
- Review ATED Relief Declarations: Verify that commercial letting relief declarations are filed annually and that tenancy agreements withstand HMRC scrutiny for connected persons.
- Stress-Test PRR Assumptions: Run scenario analyses on estates where primary residence values exceed £2 million to quantify client exposure should Private Residence Relief be restricted.
- Coordinate with Panel Valuers: Establish formal referral networks with specialist RICS-accredited valuers capable of providing expert witness-level documentation for contentious filings.
Strategic Realignment
The dismissal of a £1.5 million mansion tax has brought relief to mid-market homeowners, but it has sharply drawn the battle lines around the £2 million prime threshold. For UK private client accounting professionals, success in the coming fiscal year will not come from passive waiting. By deploying defensible valuation frameworks, auditing enveloped holdings, and executing tailored family wealth restructuring, practitioners can shield their clients from sudden fiscal shifts while positioning their firms as indispensable strategic advisers.