
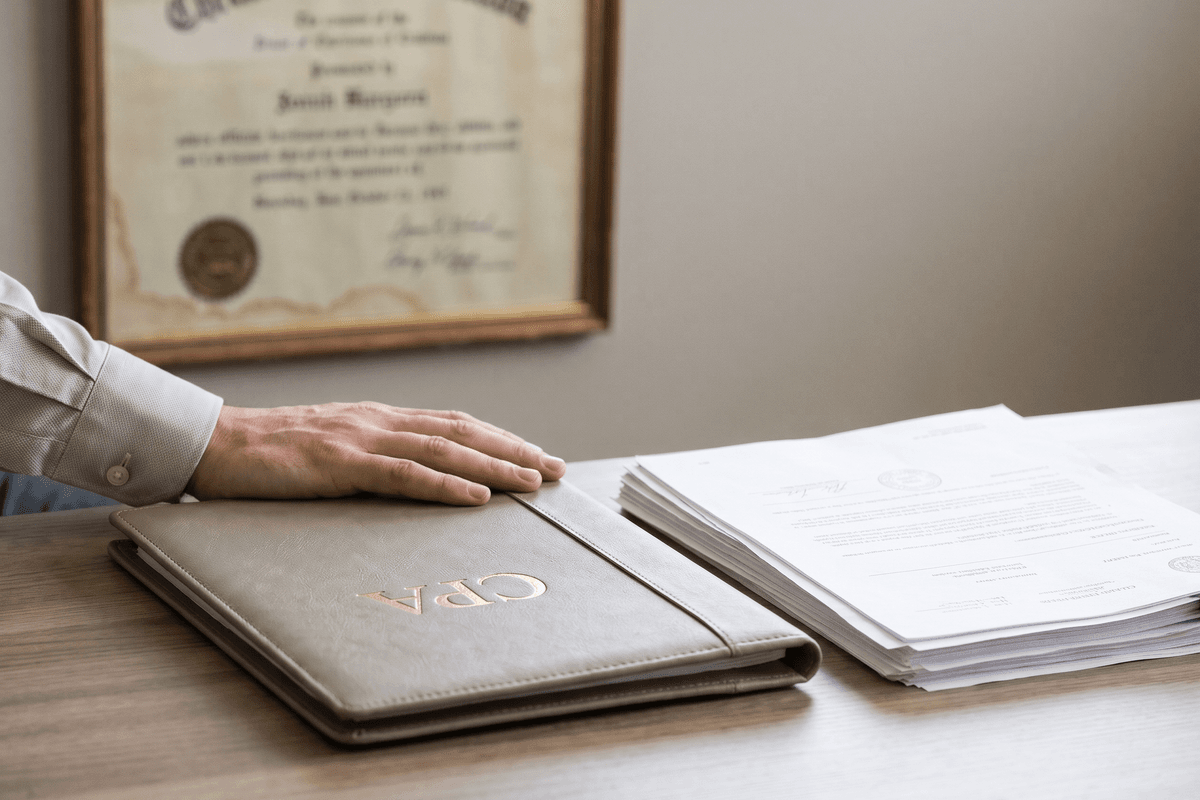
Résumés are supposed to open doors, not end careers. Yet every hiring cycle, some candidates are tempted to inflate a credential, overstate an experience level, or claim a designation they have not actually earned. A recent disciplinary matter reviewed by Going Concern makes one point painfully clear: in the eyes of Canadian regulators, misrepresenting your licence during recruitment is not a minor slip. It is a professional conduct issue, and it is one that the profession takes seriously.
What the Case Tells Us
The commentary centres on a decision issued by the Chartered Professional Accountants of British Columbia (CPABC). Going Concern's headline captures the core lesson with a pointed phrase: "reckless disregard for the truth" is not a skill firms are looking to hire for. The phrase matters because it signals that regulators do not need proof of a deliberate lie to act. A careless or indifferent approach to the accuracy of a credential claim can be enough to raise serious questions about a member's integrity.
"It seems 'reckless disregard for the truth' is not an in-demand CPA skill."
Going Concern, headline of its review of the CPABC disciplinary decision
For accounting professionals, the takeaway is that credibility is a professional asset that compounds over a career. A single misstatement about licensure can overshadow years of solid work, especially in a profession where clients and employers rely on the designation as a shorthand for competence and ethics.
Why Licensure Claims Carry So Much Weight in Canada
Canada's accounting profession operates through provincial and territorial bodies that govern membership, practice rights, and discipline. Since the unification of the designation, the Chartered Professional Accountant (CPA) title is shared across the country, but the regulator that holds your membership is still provincial. That distinction matters. A candidate may hold a CPA designation in one province yet be claiming a practice right, a public accounting licence, or a status that applies only in another jurisdiction. Each of these claims can be checked against the public registers maintained by the relevant body. For more on the national framework, see CPA Canada.
Common Claims That Require Verification
| Type of Claim | Why It Matters | How to Verify |
|---|---|---|
| CPA designation held | Confirms the individual completed the required education, examinations, and experience | Search the provincial body's public membership directory |
| Current membership status | Lapsed or suspended members cannot practise or use the designation | Confirm active status directly with the regulator on the date of the claim |
| Public accounting licence or practice rights | Determines whether the person can sign assurance or other attest reports | Check the provincial registry and any firm permit requirements |
| Years of experience or training hours | Often a condition of membership and a frequent point of exaggeration | Request confirmation through the candidate's training office or supervisor |
| Jurisdictional history | Reveals prior discipline, conditions, or transfers between provinces | Ask for a certificate of standing or check disciplinary publications |
How Regulators Monitor Compliance
Provincial bodies do not rely solely on complaints. Monitoring is often built into the lifecycle of a member, and misrepresentation can surface through several channels. The following sequence reflects the general pattern of how such matters typically come to light:
- Detection: A discrepancy is flagged by a prospective employer, a client, a complainant, or a routine compliance review.
- Verification: The regulator checks the claim against its membership and licensing records.
- Investigation: Staff gather documents and ask the member to explain the representation.
- Hearing or resolution: The matter may be resolved through a consent process or heard by a discipline committee.
- Outcome: Sanctions can range from reprimands and conditions to fines, suspension, or expulsion, and decisions are often published.
Publication is a key point. Discipline decisions create a public record. A hiring manager who searches a candidate's name may find the outcome long after the recruitment process ended, which means a short-term embellishment can have a long-term reputational cost.
Practical Implications for Firms
Recruitment is where many licensure problems begin, and it is where firms have the most control. Hiring teams that treat verification as a routine step, rather than an awkward formality, reduce both regulatory exposure and client risk.
- Verify every designation and status claim against the provincial registry before an offer is made.
- Document the verification with dates, screenshots, or confirmation letters kept on file.
- Ask for explanations when a résumé and a registry record do not match, rather than assuming bad faith or ignoring the gap.
- Re-verify periodically, because membership status can change after hiring.
- Set a clear policy on misrepresentation so employees understand the consequences before a problem arises.
Why Firms Share Responsibility
A firm that employs a member whose licence is misrepresented may face questions about its own supervision, its use of the designation in client materials, and its governance. Firms that practise public accounting also have obligations under their own permit requirements. Recruitment diligence is therefore part of firm risk management, not just human resources.
Practical Implications for Individual CPAs
For individual professionals, the lesson is less about fear and more about discipline. Keeping your credentials accurate is straightforward when you treat your professional profile as a regulated document.
Protecting Your Credibility
- Audit your own profile across résumés, LinkedIn, firm bios, and proposals at least once a year.
- Use the exact designation language that your provincial body specifies, and avoid implying rights you do not hold.
- Keep your membership current and track renewal deadlines, practice permit obligations, and continuing professional development requirements.
- Correct errors promptly. A prompt correction is far better than a regulator discovering the mistake first.
- Seek guidance from your provincial body or a professional advisor when you are unsure how to describe your status.
Looking Ahead
The growing use of online registries, automated background checks, and digital credential verification means that discrepancies are becoming easier to detect, not harder. Firms should expect that a recruitment file will be scrutinised by someone, somewhere, and candidates should assume the same. As the profession continues to emphasise public trust, we can expect regulators to keep treating licensure accuracy as a core element of professional conduct.
For Canadian accounting professionals, the path forward is clear. Verify before you claim, verify before you hire, and treat accuracy as a daily professional habit. The most in-demand skill in the CPA profession is not a particular technical specialty; it is the reliability that makes clients and employers willing to trust your word. Build that reputation carefully, because it is far easier to protect than to rebuild.