
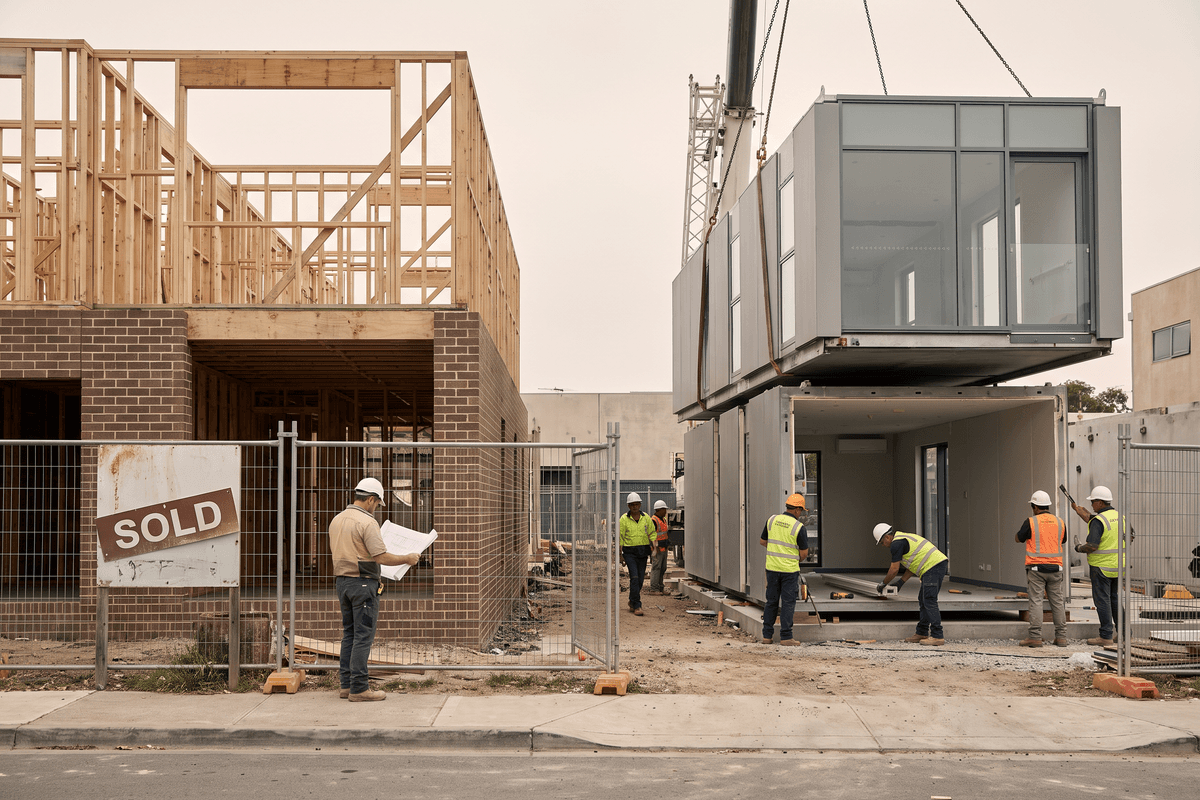


The UK construction sector is confronting a persistent divergence in demand as autumn 2026 approaches. According to the latest official figures from the Office for National Statistics (ONS), total construction output in Great Britain fell by 1.0% in the three months to August 2026. This ongoing contraction continues to be anchored by prolonged weakness in speculative residential development, where private new housing output dropped by 3.2% over the same period. Yet beneath these headline drops lies a starkly bifurcated operating environment: while traditional residential housebuilders face sluggish absorption rates and high development finance hurdles, agile contractors leveraging Modern Methods of Construction (MMC) are capturing robust public sector and healthcare infrastructure pipelines.
Inside the August 2026 ONS Figures: The Anatomy of a Contraction
The ONS data reflects the cumulative friction of persistent interest rates, planning delays, and cautious consumer sentiment across private residential markets. Over the three-month rolling window to August 2026, the volume of construction output slipped across both new work and repair and maintenance (R&M), but the heaviest drag remains concentrated in speculative housing.
Private new housing, historically the engine room of national volume output, saw a decisive 3.2% quarter-on-quarter drop. This reflects developers deliberately pacing phased rollouts, curtailing land purchases, and focusing cash flow on completing standing inventory rather than breaking ground on speculative multi-phase schemes.
| Sector / Measure | 3-Month Rolling Trend (to August 2026) | Primary Market Driver | Operational Implication for Contractors |
|---|---|---|---|
| Total Construction Output | -1.0% | Broad macro caution and private sector delays | Selective bidding and tighter cashflow management |
| Private New Housing | -3.2% | Elevated mortgage costs and developer hesitation | Downscaling speculative groundworks; margin pressure |
| Public Non-Housing / Healthcare | Positive / Resilient | NHS Trust estate upgrades & elective surgery capacity | High demand for turnkey MMC and rapid offsite delivery |
| Repair & Maintenance (R&M) | Flat to Marginal Decline | Postponed discretionary commercial refits | Focus shifting to regulatory and compliance upgrades |
While the private housing market remains subdued, non-housing public sector output—bolstered by healthcare trusts, educational estate upgrades, and civic infrastructure—has provided a critical floor for output volumes. For main contractors and specialist trades, survival and growth in this environment require an aggressive pivot away from over-reliance on volume residential subcontracts.
The Public Sector Silver Lining: Healthcare Infrastructure and MMC Delivery
The resilience of public non-housing is exemplified by targeted capital deployments across the National Health Service. Facing elective recovery targets and ageing estate backlogs, NHS Trusts are increasingly bypassing lengthy traditional builds in favour of high-precision modular construction to deliver urgent clinical capacity without disrupting active hospital operations.
A prime example of this operational shift is the recent appointment at The Shrewsbury and Telford Hospital NHS Trust (SaTH), which has commissioned specialist offsite healthcare contractor ModuleCo as the principal contractor to deliver a state-of-the-art 240-square-metre ophthalmic operating theatre suite at the Royal Shrewsbury Hospital.
"Modular construction allows health trusts to achieve rapid clinical commissioning with minimal site disruption, bypassing traditional multi-year build programmes in favor of factory-controlled precision."
Projects of this calibre illustrate why modular delivery is cementing its status across healthcare procurement frameworks:
- Accelerated Delivery Timelines: Offsite volumetric fabrication occurs concurrently with onsite groundworks and substructure engineering, cutting handover schedules by up to 50% compared to traditional in-situ methods.
- Operational Continuity: Clinical environments demand strict vibration, dust, and acoustic controls. Offsite assembly dramatically reduces on-campus site traffic and noise footprint, allowing acute hospital wards to function uninterrupted.
- HTM & HBN Compliance: Modern clinical suites must adhere strictly to Health Technical Memoranda (HTM) and Health Building Notes (HBN). Factory manufacturing ensures millimetre-level quality control across specialised air filtration, medical gas installations, and sterile containment zones.
Why MMC is Winning NHS Capital Allocations
As the ONS figures demonstrate, speculative commercial and residential development cycles are heavily exposed to macroeconomic swings. In contrast, healthcare trusts operate under acute operational mandates to clear surgical backlogs. The Royal Shrewsbury Hospital ophthalmic facility will provide dedicated day-case eye surgery capacity, directly reducing waitlists across Shropshire and Mid Wales.
For main contractors, partnering with established offsite specialists or acquiring volumetric fabrication capabilities provides direct access to high-margin, ring-fenced public framework spend that is insulated from private mortgage and consumer sentiment trends.
Strategic Playbook for Contractors: Navigating Late 2026
With total output contracting by 1.0%, construction leadership teams cannot afford passive commercial positioning. Navigating the remainder of 2026 demands decisive operational realignments:
- Diversify Order Books into Ring-Fenced Frameworks: Rebalance pipeline exposure away from speculative housing developers and toward public sector procurement portals (such as NHS Shared Business Services, Procure23, and Crown Commercial Service frameworks).
- Integrate Modular and Hybrid Construction Workflows: Subcontractors must upskill their workforce in mechanical, electrical, and plumbing (MEP) modular integration, offsite structural connections, and rapid commissioning protocols to qualify for Tier-1 supply chains.
- Rigorous Working Capital Management: In a contracting volume environment, Tier-1 and Tier-2 contractors must scrutinise client credit risks, lock in robust milestone payment mechanisms, and avoid fixed-price long-cycle contracts that carry unhedged inflation exposure.
- Focus on Specialist Niche Delivery: High-specification fit-outs—such as operating theatres, cleanrooms, and data centre infrastructure—command far stronger margin resilience than commoditised core-and-shell residential works.
The Road Ahead: Building for Resilience
The August 2026 ONS output figures serve as a sobering reminder of the structural drag created by private residential sluggishness. However, viewing the industry through a purely negative lens misses the vital re-engineering taking place across the sector. Contractors that anchor their commercial strategies in public sector healthcare, rapid offsite delivery, and high-performance engineering are not merely weathering the 1.0% contraction—they are establishing long-term competitive advantages that will define the UK construction landscape well into 2027.