
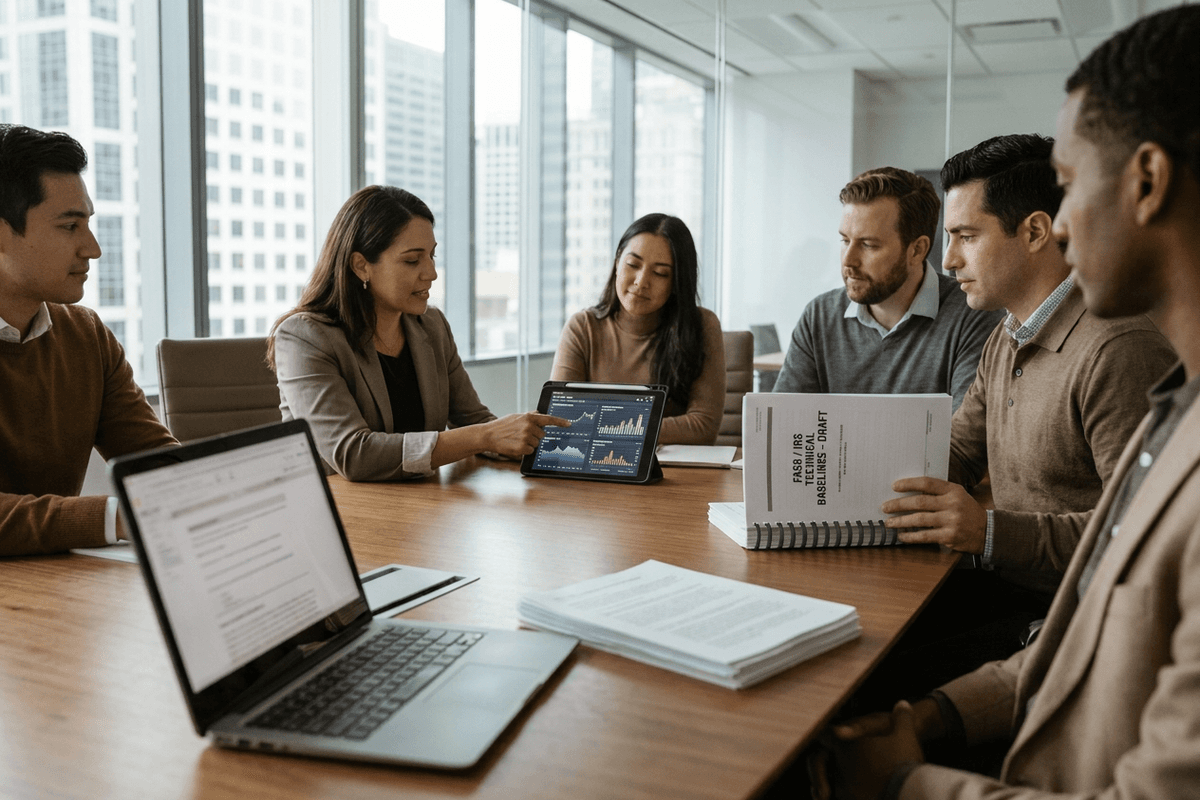
For the past three years, corporate boardrooms and industry prognosticators warned of a looming headcount contraction across corporate finance and public accounting, predicting that generative models and automated workflow agents would gut entry-level ranks and trim mid-tier analytical teams. However, newly released empirical data demonstrates that the reality within corporate treasury and accounting suites is unfolding quite differently. Rather than discarding accounting talent, corporate leaders are aggressively pivoting their teams toward higher-margin, judgment-heavy mandates.
According to a comprehensive survey of 270 U.S. chief financial officers and senior finance executives, a mere 3% reported actively reducing headcount in response to artificial intelligence adoption. In stark contrast, 60% of finance leaders confirmed that AI tools have enabled them to redeploy existing staff to strategic forecasting, risk mitigation, and advisory functions. As automation absorbs transactional reconciliation and structured data entry, accounting professionals are finding themselves elevated into internal strategic partners—just as standard-setters and tax authorities roll out intricate new compliance frameworks that demand elevated human oversight.
The Anatomy of the Redeployment Dividend
The transition from manual transaction processing to strategic advisory is not merely an aspirational cultural shift; it is an operational imperative driven by margin defense and talent retention. Corporate finance departments face mounting complexity across domestic tax planning, supply chain accounting, and algorithmic integration. Eliminating personnel who possess institutional memory in exchange for unassisted machine automation has proven to be an untenable risk profile for modern CFOs.
"Finance teams are discovering that operational automation does not reduce the demand for financial acumen; it amplifies the demand for professional skepticism, data storytelling, and real-time business partnering."
Instead of executing workforce reductions, forward-thinking finance leaders are orchestrating deliberate reskilling initiatives designed to channel freed-up labor hours into four primary domains:
- Predictive Scenario Modeling and Capital Allocation: Shifting backward-looking monthly close commentary into dynamic, forward-looking cash flow and liquidity forecasting.
- Cross-Functional Business Unit Partnering: Embedding senior accountants alongside operational leads to analyze unit economics, contract pricing structures, and real-time margin leakage.
- Internal Control and Algorithm Validation: Establishing oversight mechanisms to verify that automated enterprise resource planning (ERP) pipelines remain compliant with internal controls over financial reporting (ICFR).
- Regulatory Gap Analysis: Proactively auditing vendor contracts and customer incentive arrangements against evolving accounting standards.
Assuring the Algorithms: AICPA’s New Dual-Assurance Standard
As corporate finance suites rely more heavily on autonomous algorithms to handle transactional velocity, corporate audit committees and external stakeholders require verifiable proof of algorithmic integrity. Recognizing that traditional control testing must evolve, the profession has moved rapidly to establish formal assurance mechanisms for artificial intelligence.
In a landmark collaboration, the AICPA teamed up with the Artificial Intelligence Underwriting Company (AIUC) to launch a unified assurance framework. This offering merges traditional SOC 2 attestation with rigorous, objective AIUC-1 technical testing for AI systems and autonomous agents. The initiative equips practitioners to audit machine-learning architectures for bias, data lineage, algorithmic drift, and deterministic accuracy—providing the exact governance umbrella CFOs require as they integrate agentic automation into financial reporting.
| Assurance Dimension | Traditional SOC 2 Framework | AICPA & AIUC-1 Dual Framework |
|---|---|---|
| Core Focus | System availability, data confidentiality, security, and processing integrity. | Technical model validation, algorithmic safety, deterministic testing, and agentic governance. |
| Testing Target | Static IT general controls (ITGCs) and infrastructure perimeter defenses. | Dynamic model behaviors, data training lineage, model hallucination thresholds, and drift control. |
| CPA Firm Application | Information technology and cybersecurity readiness attestations. | Specialized algorithmic attestation for autonomous finance agents and enterprise AI deployments. |
Technical GAAP Refinements: FASB Tackles Consideration Payable to Customers
While algorithmic tools liberate internal capacity, standard-setters are ensuring that technical GAAP interpretation remains demanding. The Financial Accounting Standards Board has moved to resolve persistent divergence in practice under ASC Topic 606 (Revenue from Contracts with Customers).
The FASB issued a proposed Accounting Standards Update aimed at clarifying Topic 606 rules regarding consideration payable to a customer. Currently, corporate preparers face significant ambiguity when evaluating whether payments, rebates, slotting fees, or equity instruments granted to entities within the broader customer distribution chain must be recorded as a reduction of revenue or as an operating expense.
Key Dimensions of the Proposed ASU
- Distribution Chain Scoping: Broadening the definition of a customer to explicitly encompass indirect customers, such as retailers purchasing goods through third-party distributors.
- Distinct Goods and Services Assessment: Establishing explicit evaluation criteria to determine whether consideration received from a vendor represents a genuine payment for distinct goods or services at fair value.
- Pervasive Industry Impact: Consumer packaged goods (CPG), pharmaceutical, and retail-adjacent enterprises must re-evaluate thousands of co-op advertising agreements and volume discount schedules.
This technical realignment provides an immediate proving ground for redeployed finance professionals. Rather than spending weeks manually compiling journal entries, senior accountants are now tasked with leading cross-functional contract reviews alongside legal and sales operations to establish compliant revenue schedules.
Tax Operations in Flux: IRS Direct Card Processing and Targeted Diesel Relief
The convergence of operational modernization and regulatory calibration is equally pronounced in corporate taxation and treasury management. Recent actions from the Department of the Treasury and the Internal Revenue Service highlight both digital transformation and sector-specific compliance relief.
On the infrastructure front, the IRS finalized regulations implementing Taxpayer First Act provisions that allow taxpayers and commercial entities to submit electronic card payments directly to the agency without routing transactions through third-party intermediary payment processors. By eliminating intermediary processing friction and third-party fee markup overhead, corporate tax departments gain streamlined payment execution, simplified reconciliation schedules, and real-time ledger settlement verification directly through IRS portals.
Simultaneously, the agency has demonstrated tactical flexibility in administrative enforcement. In targeted guidance, the IRS waived rigid dyed diesel fuel recordkeeping requirements for specific commercial purchasers and fleet operators. Dyed diesel—traditionally restricted to non-highway agricultural and industrial use and exempt from standard federal fuel excise taxes—has historically carried severe compliance and audit liabilities for minor record omissions. The temporary waiver alleviates administrative gridlock for supply chain operators while providing tax advisors clear parameters to protect commercial clients from erroneous excise penalties.
Strategic Action Plan for CPA Firms and Corporate Controllers
To capitalize on the redeployment dividend and protect organizations against operational and regulatory volatility, leadership teams must execute a balanced strategic roadmap across talent, tech, and compliance:
- Formalize an Internal Reskilling Curriculum: Identify corporate finance team members whose transactional duties have been automated and enroll them in specialized training focused on contract evaluation (Topic 606), data visualization, and advanced FP&A scenario engineering.
- Establish Algorithmic Assurance Protocols: If your organization deploys autonomous bots for invoice matching, journal entry generation, or tax provision estimates, adopt the AICPA/AIUC-1 dual-assurance standards to validate internal controls before external audit cycles commence.
- Audit Customer-Facing Incentive Programs: Convene an ASC Topic 606 task force to inventory all marketing allowances, slotting arrangements, and customer rebates to assess the balance sheet impact of FASB’s upcoming consideration-payable guidance.
- Modernize Corporate Tax Settlement Pipelines: Update internal treasury workflows to integrate direct IRS payment protocols, reducing transactional fees and eliminating third-party processor security vulnerabilities.
The narrative that artificial intelligence would hollow out the accounting and finance profession has been upended by operational reality. As machines assume the burden of repetitive data synthesis, human judgment, regulatory acumen, and strategic guidance have become more indispensable than ever. Practitioners and corporate leaders who leverage this window to reskill their teams will establish enduring competitive advantages in an increasingly automated economy.