
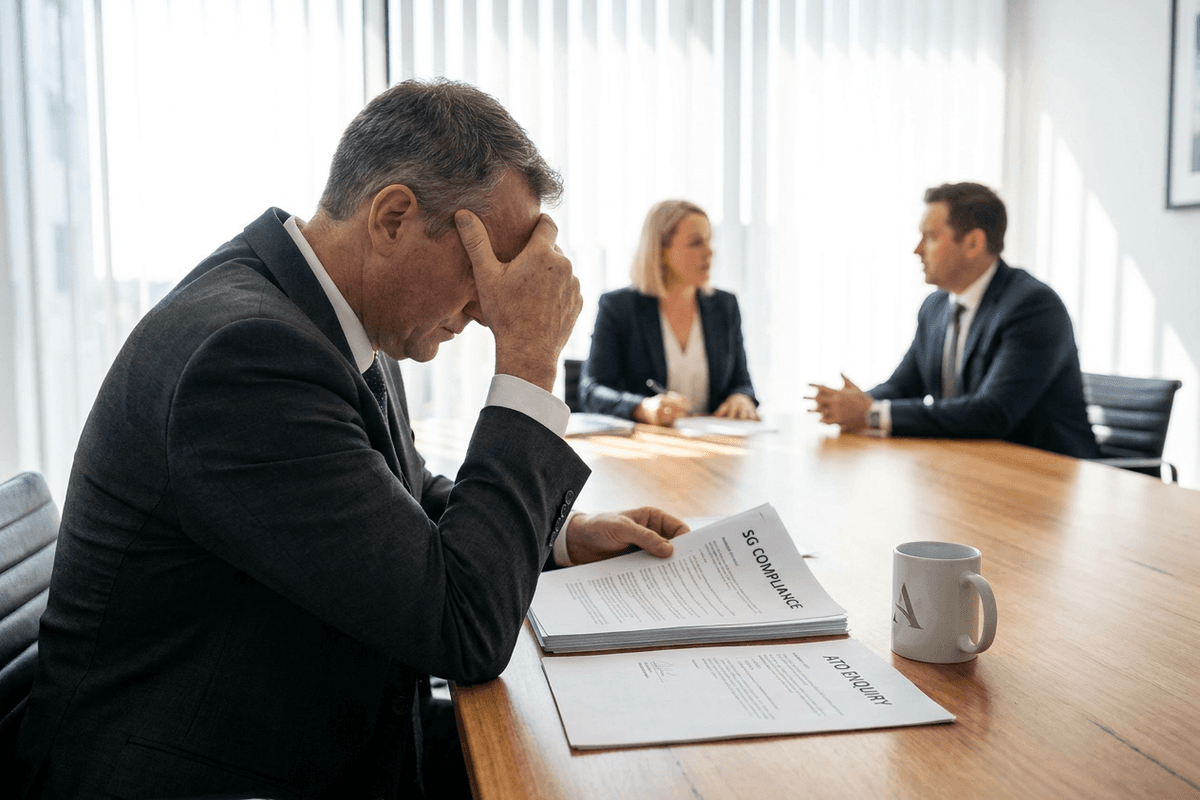
When automated regulatory enforcement collides with the messy reality of small business payroll, public practice accountants invariably find themselves stationed in the blast radius. In recent appearances before the Senate Economics Legislation Committee, senior officials from the Australian Taxation Office (ATO) faced intense scrutiny over alleged systemic data-matching errors that triggered wave upon wave of incorrect Superannuation Guarantee Charge (SGC) warning letters to small business employers. For practitioners on the front line, the Senate grilling merely confirmed what their timesheets have documented for months: Canberra’s data algorithms are triggering unprompted client panic, creating unbillable reconciliation work, and exposing firms to unprecedented friction.
The controversy arrives at a dangerous juncture for Australia's accounting profession. A dramatic hardening in the ATO’s post-pandemic debt collection stance has already triggered a staggering 180% surge in complaints to the Taxation Ombudsman over the past two years. Compounding this pressure, the Tax Practitioners Board (TPB) is exercising an aggressively expanded sanction regime, handing down 162 compliance sanctions in 2025–26 alone. Between algorithmic administrative errors, unbending debt recovery, and rising professional liability, Australian tax agents are being forced to absorb the operational shock of an increasingly automated compliance regime.
The Algorithmic Disconnect: Dissecting the SGC Data Failure
At the core of the Senate inquiry lies the ATO’s automated data-matching protocol, designed to cross-examine employer-reported payroll data against contributions acknowledged by receiving superannuation funds. The intent of modern compliance—underpinned by STP Phase 2 and SuperStream reporting—is near real-time transparency. However, the operational reality has exposed critical structural vulnerabilities.
Practitioners and corporate restructuring specialists have repeatedly sounded the alarm over warning letters threatening backbreaking SGC penalties, Part 7 penalties of up to 200%, and nominal interest charges sent to compliant business owners. In dozens of instances presented to the Senate, employers had disbursed contributions days before the statutory quarterly cutoff, only for commercial clearing house processing windows, bank batching delays, or super fund allocation queues to register the cash days after the deadline.
"The chasm between tax administration software and real-world banking infrastructure is penalising honest business owners. When an automated system presumes guilt before human verification, the cost of disproving that error falls squarely on the taxpayer and their accountant." — Insolvency and Restructuring Practitioner Submission to Senate Committee
Crucially, the statutory mechanics of the Superannuation Guarantee (Administration) Act 1992 offer no administrative grace for transmission lag. Under the letter of the law, contributions are only deemed "paid" when received by the trustee of the complying super fund—with the sole legislative exception being payments made directly into the ATO’s own Small Business Superannuation Clearing House (SBSCH). When third-party payroll engines send contributions on the 25th of the month and an APRA-regulated fund books the receipt on the 29th, the ATO's automated scanners register an immediate SGC default. The result is an avalanche of demand letters that ignore commercial realities.
The Compliance Squeeze: Debt Enforcement Meets the Ombudsman Surge
The SGC data saga cannot be viewed in isolation; it is symptomatic of an aggressive enforcement pivot within the ATO. After pausing standard recovery activity during the COVID-19 pandemic, the regulator has aggressively resumed collectable debt recovery, driving total small business tax debts to historic highs.
This uncompromising stance has led to a historic flashpoint. Data from the Inspector-General of Taxation and Taxation Ombudsman (IGTO) reveals an alarming trajectory: complaints against the ATO have skyrocketed by 180% across the 2024–2026 reporting cycles. Small business operators and their advisers report an administrative apparatus unwilling to exercise commercial flexibility, refusing General Interest Charge (GIC) and Shortfall Interest Charge (SIC) remissions even where operational disputes stem from software or data-matching failures.
| Regulatory Pressure Point | 2024 Baseline Status | 2026 Current Environment | Direct Impact on Accounting Practices |
|---|---|---|---|
| Taxation Ombudsman Complaints | Standard pre-pandemic dispute baselines | Surged 180% over a 24-month horizon | Massive increase in unbillable client dispute advocacy and escalation filings |
| SGC Enforcement Protocol | Audit-prompted, manual casework reviews | Automated STP Phase 2 data-matching letters | Surprise Director Penalty Notice (DPN) risks and false-positive reconciliations |
| TPB Disciplinary Actions | Standard educational and compliance monitoring | 162 formal sanctions (incl. 67 license terminations) | Extreme personal and firm liability under expanded ministerial Code obligations |
| Debt Recovery & GIC Stance | Flexible installment plans and routine remissions | Strict recovery, aggressive DPNs, automated wind-up notices | Client solvency crises, cash-flow friction, and strained banking covenants |
When automated warning letters threaten directors with personal liability via Director Penalty Notices (DPNs) for SGC shortfalls that do not legally exist, business owners turn to their accountants in a panic. Firms are forced to redirect senior tax managers away from high-value advisory work to conduct manual, transaction-by-transaction reconciliations across payroll ledgers, clearing house logs, and employee fund statements—all to disprove an algorithmic assumption.
The Policy Blindspot: Skilled Migration and the 'Accountant Deficit'
The administrative burden generated by faulty tax notices is hitting an industry already operating at breaking point. Across Australia, accounting firms continue to grapple with a structural talent deficit exceeding 17,000 professionals, a bottleneck that makes absorbing automated compliance errors exceptionally costly.
Despite these well-documented staffing pressures, the profession has faced bizarre political headwinds. Recent populist suggestions, notably from One Nation leader Pauline Hanson advocating to exclude accountants from skilled migration programs, have drawn fierce pushback from professional bodies and recruiters. Industry leaders point out that public practice accountants are the primary integrity buffer protecting the Australian tax system from complete collapse. Stripping migration avenues while Canberra piles on administrative complexity demonstrates a profound misunderstanding of economic infrastructure.
When policymakers treat accounting as an administrative cost rather than critical economic infrastructure, systemic failures like the SGC data saga occur. The profession is being asked to digest real-time reporting mandates without the workforce capacity required to triage the resulting errors.
The Pincer Movement: TPB Sanctions and Expanding Code Liabilities
While practitioners burn billable hours resolving ATO algorithmic errors, the regulatory perimeter around their own conduct has never been tighter. The Tax Practitioners Board’s 2025–26 Annual Report details an unprecedented enforcement campaign: 162 total sanctions, including 67 outright terminations and 66 formal cautions. Armed with expanded ministerial sanction powers and a revitalised Code of Professional Conduct, the board has made it clear that passive reliance on third-party data or administrative shortcuts will be met with career-ending penalties.
This creates an acute liability trap for public practitioners managing SGC disputes:
- Due Care and Reasonable Verification: A practitioner cannot simply accept a client’s payroll clearing house confirmation at face value if the ATO has issued an SGC warning. Advisers are legally bound to verify whether the funds actually landed in the complying fund before the statutory cutoff.
- Conflict of Duty and Disclosure: If an accountant discovers that an SGC shortfall did in fact occur due to their own firm's payroll management processing delays, expanded obligations around honesty, client communication, and error remediation trigger severe ethical and insurance hurdles.
- Liability for Unrectified Non-Compliance: With the TPB’s heightened scrutiny on regulatory cooperation, practitioners risk disciplinary intervention if they fail to advise clients accurately on their obligations to self-lodge SGC Statements—even when the underlying discrepancy originated from an ATO data mismatch.
A Moving Feast of Legislative Overhauls
The operational chaos generated by the SGC data saga is unfolding against a broader backdrop of relentless legislative change. Practitioners are simultaneously preparing clients for structural tax overhauls detailed in the Treasury Laws Amendment Bill 2026, which reshapes small business capital gains tax (CGT) treatment, research and development thresholds, and transition protocols for monthly Pay-As-You-Go (PAYG) installments.
Furthermore, managing client asset realisations has become treacherous. Prominent tax advisers have cautioned that the ongoing "moving feast" of CGT reform—particularly around complex market valuation standards and goodwill calculations—presents severe compliance hurdles for mid-tier practitioners. This structural compliance deluge stretches into the superannuation sector, where fresh benchmarking indicates that SMSF audit practices face an unprecedented capacity crunch leading into 30 June rather than traditional spring deadlines.
When ATO systems misfire on core payroll and super compliance, they drain firm bandwidth precisely when partners need their teams focused on navigating these complex legislative shifts.
Strategic Blueprint: How Accounting Firms Must Respond
Accounting leaders cannot afford to treat automated ATO warning letters as isolated administrative hiccups. Firms must insulate themselves and their clients from data-matching errors through deliberate operational changes.
1. Enforce a Strict "Cutoff Minus 7" Payroll Rule
Because the ATO does not recognize commercial clearing house processing times as safe harbours under section 23(1) of the SGAA 1992, firms offering managed payroll services must mandate an uncompromising processing timeline. Client payroll batches for quarterly super must be authorised, cleared, and released to third-party clearing houses at least seven full business days prior to the statutory 28-day quarterly deadline (e.g., by 21 October, 21 January, 21 April, and 21 July). Clients who refuse to adhere must sign formal indemnities acknowledging potential SGC and Part 7 liability.
2. Productise Automated Warning Letter Triage
Stop absorbing the cost of ATO false positives. Update practice engagement letters to explicitly classify responses to unprompted ATO automated compliance notifications as separate, out-of-scope compliance reviews. Build a standardized reconciliation workflow within your practice management software that rapidly extracts STP Phase 2 transaction IDs, bank debit stamps, and SuperStream allocation timestamps into a single, pre-formatted audit response packet.
3. Audit the Clearing House Architecture
Review every client's super disbursement pipeline. Where micro and small business clients continue to process super through commercial add-on portals prone to multi-day batching bottlenecks, evaluate whether transitioning them to the ATO’s SBSCH provides a safer legal shield. Under the SBSCH regime, an employer’s legal superannuation obligation is discharged the exact moment payment is successfully accepted by the clearing house, completely neutralizing downstream APRA-fund processing lags.
4. Implement Immediate DPN Escalation Protocols
Given the ATO’s zero-tolerance stance on debt recovery, any correspondence indicating potential unpaid SGC must trigger an internal red alert. A false SGC calculation that remains unaddressed can quickly result in an automated 21-day Lockdown Director Penalty Notice, personalizing corporate liabilities for client directors. Establish a firm-wide rule: SGC correspondence must be escalated to a partner and responded to in writing within 48 hours of receipt.
The Road Ahead: Navigating Algorithmic Tax Administration
The Senate Economics Committee's examination of the ATO’s SGC data matching exposes a broader systemic shift: Australian tax administration is becoming digitized, automated, and decoupled from discretionary human judgment. While the ATO will inevitably calibrate its algorithms to smooth over these high-profile discrepancies, the underlying trajectory is irreversible.
For Australian accounting practices, survival and profitability require abandoning any assumption that official tax notices are inherently accurate. In an era of robotic enforcement, skyrocketing Ombudsman disputes, and aggressive TPB oversight, the public practice accountant's value lies not merely in calculating numbers, but in acting as an indispensable firewall between the small business economy and an imperfect automated state.